AI Is Replacing Workers, Margins Are Expanding, and the Market Is Rewarding It
Markets are near all-time highs as AI-driven productivity expands margins, even amid layoffs, war risk, and inflation pressure. Explore the $166B tariff refund stimulus, rate outlook, insider AI concerns, and the SpaceX/xAI race.
This is one of those moments when Wall Street and Main Street are clearly looking at the same facts and reaching very different conclusions.
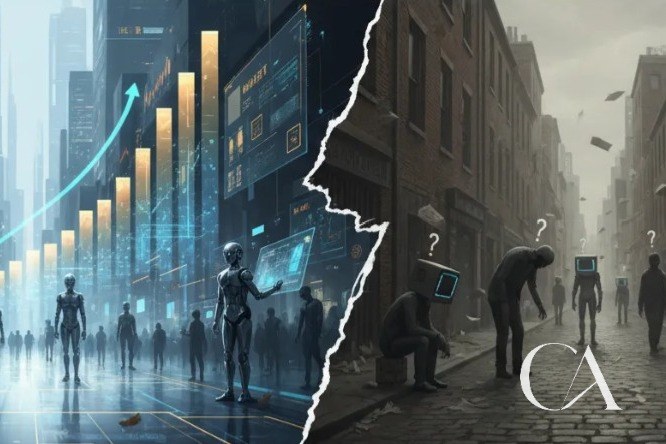
On one side, companies are cutting jobs, consumer anxiety is rising, and a growing share of Americans expect unemployment to worsen over the next year. On the other side, stocks are near all-time highs, investors are paying up for AI exposure, and the market is acting as if the next productivity boom is already locked in.
That disconnect is the story.
The bullish case is simple: AI allows companies to do more with fewer people, productivity rises sharply, margins expand, and equity values move higher. The bearish case is just as simple: labor displacement happens faster than the economy can absorb it, unemployment rises, confidence falls, and policymakers are caught flat-footed.
Right now, the market is clearly voting for the first outcome.
Below is the full framework behind that view, including the tariff refund stimulus, why stocks are still near highs despite war and inflation pressure, what AI insiders are now saying behind closed doors, how layoffs fit into the investment thesis, what to make of the SpaceX and xAI strategy, and why the debate over holding versus selling elite private assets is getting more important.
1.Quick summary: what matters right now
Roughly $166 billion in tariff refunds owed to businesses functions like a fresh stimulus for an economy that was already growing.
That kind of fiscal boost supports GDP, but it also argues for higher rates for longer and a steeper yield curve.
Stocks recovered sharply from war-related oversold levels and are again trading near all-time highs.
The market is increasingly pricing an AI-led productivity boom, even as layoffs rise.
Meta and Amazon job cuts are being framed as AI efficiency moves, and markets are rewarding them.
Headline unemployment is 4.3%, but broader labor stress looks worse when using wider measures like U-6 at 7.9%.
AI insiders are reportedly more concerned about regulation now than they were a year ago because model development is accelerating faster than expected.
Massive new compute capacity is still coming online, which suggests the current AI wave may be early rather than late.
SpaceX, xAI, and Elon Musk’s push for talent and scale reflect a larger race to avoid falling behind OpenAI, Anthropic, and others.
Rate cuts in the US are still plausible later this year, even with near-term inflation pressure from energy and war.
2.The $166 billion tariff refund is effectively a new stimulus
One of the less discussed developments is the roughly $166 billion in refunds owed to businesses rather than consumers. Large companies including Walmart and Target are among those tied to the issue.
From a macro perspective, this is straightforward. Money flowing back to corporations is stimulus. It supports activity. It boosts GDP. And because it lands in an economy that is already holding up reasonably well, it also increases the chance that policy stays tighter for longer.
That has several implications:
Growth gets an extra tailwind.
The Treasury likely needs more debt financing.
The yield curve should steepen.
Rate cuts may come later than markets initially hoped.
That matters because the market has spent much of the last year trying to balance two opposing forces: stronger-than-expected growth and the desire for lower rates. More stimulus makes that balancing act harder.
At the same time, there is a separate policy narrative building around Kevin Warsh and the belief that AI-driven productivity could create room for easier monetary policy later. The thinking there is that if AI creates meaningful disinflation through productivity gains, then the Fed may eventually tolerate cutting even if the economy remains stronger than expected.
That is a powerful argument, but it is not an immediate one. In the short run, fiscal support and persistent consumption can keep rates elevated.
3.Why are markets near all-time highs with war, higher gas prices, and inflation pressure?
This is the question many investors keep asking: how can stocks be trading this well when geopolitical risk is elevated, gasoline prices have surged, and the market appears to be pricing near perfection?
The answer begins with positioning.
Markets had become heavily oversold at the peak of the war scare. When that happens, relief rallies can be violent. In this case, the S&P 500 reportedly rallied roughly 14% from the late-March low near 6,400 into late April, with very few flat days in between. That is an unusually strong move in a short period of time.
When a market gets sold too hard and then rebounds, it often does one of two things:
It gives back much of the rally and retests the lows.
It keeps grinding higher because the original selloff was too extreme.
The current view is that the move may have gotten a bit overdone near term, which leaves room for a pullback toward roughly 7,000 to 7,100 on the S&P before another leg higher. But the larger trend is still seen as up because of the AI investment pipeline.
In plain language, the market is looking through near-term noise because it believes the next earnings cycle will be defined less by macro pain and more by technology-led productivity gains.
4.The core market thesis: AI is a margin expansion story first
This is the main idea driving risk assets.
From a market perspective, AI means companies will need fewer people to do more work. If labor intensity falls while output rises, profit margins expand. If margins expand, valuations can be sustained or even pushed higher.
That is why the market often reacts positively to AI-linked restructuring announcements. Investors are not treating these layoffs as cyclical distress. They are treating them as efficiency upgrades.
This is uncomfortable, but it is the cleanest way to understand current price action.
The equity market is not celebrating job losses in a moral sense. It is discounting higher future earnings.
5.Why AI insiders are suddenly more worried than they were a year ago
There is an important shift happening inside the AI community itself.
At a recent AI symposium involving major industry players, the tone reportedly changed in a meaningful way. Last year, much of the industry resisted regulation. This year, a supermajority of participants were described as believing regulation is needed.
The reason is speed.
One striking claim from that discussion was that recursive AI may be closer than many expected. In simple terms, recursive AI refers to systems that help create better versions of themselves, which then create better versions again. Once that loop becomes material, capability growth can accelerate dramatically.
Whether that timeline is exactly right matters less than the direction of travel. The people building these systems appear to believe progress is moving faster than even they expected.
That creates two simultaneous realities:
For society, this raises governance, safety, and labor disruption concerns.
For equity investors, it strengthens the argument for higher productivity and stronger margins.
This is why the market’s optimism and the industry’s anxiety can coexist.
6.Layoffs are rising, and the market is treating them as bullish
Here is where the tension becomes most visible.
Meta is reportedly cutting around 8,000 jobs, roughly 10% of the company, with the move being framed as part of an AI efficiency push. Amazon has also announced significant cuts, with a figure around 16,000 referenced in the discussion.
At the same time:
64% of Americans expect unemployment to rise over the next 12 months.
That pessimism is feeding into weaker consumer confidence readings, including University of Michigan survey data.
The official unemployment rate is 4.3%.
A broader labor distress measure, U-6, is closer to 7.9%.
That 7.9% number is not trivial. It starts to look more like the kind of labor stress people once associated with recession conditions, not a supposedly healthy economy.
So should investors fear that?
The answer depends on time horizon.
In the near term, markets appear willing to look past labor weakness because corporations are proving they can remove cost faster than revenue is weakening. In the medium term, if enough people lose income or confidence, demand can eventually weaken enough to matter for earnings.
That is the line to watch.
For now, the market believes productivity gains will outrun labor disruption. That may hold for a while. It may not hold indefinitely.
7.The clearest real-world AI example in the discussion: 50 salespeople versus one AI agent
The strongest anecdote in the conversation came from an insurance company example, and it gets to the heart of why investors are so excited.
The business had about 50 salespeople contacting doctors, psychiatrists, hospitals, and medical offices to get them to accept insurance plans and to map where those plans could be used. In a two-week period, that human salesforce signed up 90 accounts.
Then the company built an AI agent called Lucy.
AI Lucy reportedly handled the workflow end to end:
Identifying the account
Researching the business
Finding the decision-maker
Understanding current pricing and arrangements
Making contact
Pitching the plan
Negotiating the rate
The only human step left was signing the final DocuSign.
In that same general period, AI Lucy signed up 500 accounts.
That comparison was 500 for the AI system versus 90 for 50 human workers.
If even a fraction of that type of productivity gain scales across industries, the implications are enormous:
Sales and administrative roles get redefined first.
Labor cost as a percentage of revenue drops.
Middle layers of process-heavy white-collar work become vulnerable.
Software valuation multiples remain elevated because the return on implementation can be extreme.
This is why so many executives are moving quickly. They do not need AI to be perfect. They only need it to be better than the current cost structure.
8.The compute buildout suggests the AI boom may still be early
Another major point that does not get enough attention is infrastructure timing.
Large-scale data halls are now being delivered for AI clients, with one example involving an initial 130 megawatts of capacity inside what is intended to become a much larger 1.6 gigawatt campus. But the crucial observation is this: much of the current AI revolution is happening on old compute, not the new compute that is still being built and fitted out.
That means two things:
Current model progress has happened under constrained infrastructure conditions.
The next two years will bring significantly more computing power online, which may accelerate capability and adoption further.
If that is right, then current enthusiasm may not represent the end of the cycle. It may simply be the market front-running a much larger deployment wave.
This also helps explain the policy challenge ahead. More compute means more AI capability. More capability means more productivity. But it also means more disruption to employment structures and potentially faster social and political backlash.
9.What this means for the Fed and rates
The rate backdrop is more complicated than the market narrative suggests.
There are inflationary pressures coming from energy and the Middle East. If war persists and oil stays elevated, near-term inflation prints can run hot. At the same time, AI-driven productivity could become structurally deflationary over time by lowering labor cost and improving efficiency.
That leaves central banks balancing a messy mix:
Short-term inflation pressure from commodities and geopolitics
Medium-term disinflation pressure from technology and productivity
Political pressure tied to labor displacement and unemployment
The base view presented was:
US rate cuts are still likely toward the end of the year.
That can happen even if some inflation data remains hot in the near term.
Europe may have to stay tighter near term because its mandate is more directly focused on inflation.
The key issue is not just inflation itself. It is which force policymakers think will dominate six to twelve months from now.
If productivity gains begin showing up quickly enough, the Fed may be more willing to look through temporary inflation spikes.
10.SpaceX, xAI, Cursor, and the battle for AI talent
The conversation then shifted from macro and labor to one of the biggest private-market stories on the board: SpaceX.
SpaceX is being discussed around a possible valuation of roughly $1.75 trillion to $1.8 trillion, which would make it one of the largest IPOs ever, potentially larger than Saudi Aramco depending on how one measures it.
But the more interesting strategic issue is not only SpaceX itself. It is how Elon Musk is trying to use his corporate empire to stay competitive in AI.
A few points stood out:
Musk has a long history of creating enormous value for investors, which gives him unusual latitude.
He bought Twitter, then folded it into xAI.
xAI and Grok were described as trailing the leading frontier players.
He also combined non-cash-flowing businesses with stronger assets, effectively using his crown jewel ecosystem to support the AI push.
The interest in Cursor appears to be about acquiring talent and capability rapidly.
The strategic logic is obvious. If Anthropic, OpenAI, and others are pulling ahead, buying a fast-growing AI coding company is one way to compress time and import scarce expertise.
In AI, buying talent is often the same thing as buying product acceleration.
11.Will AI end up with one winner or many?
This is one of the most important investment questions in the entire space.
The historical analogy raised was search. Before Google dominated, there were multiple search engines that mattered. Then one company captured the market and effectively ate everyone’s lunch.
Could the same thing happen in AI?
The current answer is nuanced.
For AI search, there may ultimately be one clear winner. But AI is broader than search. There may be separate winners for:
Coding
Legal workflows
Portfolio management systems
Website creation
Enterprise management tools
Industry-specific vertical applications
One example mentioned was a portfolio manager who built a highly sophisticated portfolio management system over a matter of weeks using Claude extensively. Another was Harvey as a legal AI use case. The broader point is that large foundation models may underpin a very wide ecosystem of domain-specific businesses.
That argues against a simplistic winner-take-all framework for the entire category.
There may be one dominant general interface in some areas, but still many highly valuable application-layer winners above it.
12.Yes, it feels frothy. That does not mean the underlying shift is fake
Valuations in private AI are moving fast. Anthropic was discussed as trading in secondary markets around a $1 trillion valuation after having been near $350 billion only a short time earlier.
That is classic froth.
But there is a difference between a bubble in price and a delusion in substance. The view here is that even if valuations are stretched, the underlying technological shift is real and is changing every business.
That creates a difficult investing environment. You may be correct on the long-term thesis and still overpay badly in the short term.
That is why the conversation moved naturally into portfolio construction and exit discipline.
13.Holding great assets versus taking chips off the table
There were two distinct schools of thought presented on elite private winners like SpaceX and Anthropic.
View one: hold exceptional companies for a very long time
The first approach is simple. The biggest investing mistakes often come from selling quality assets too early. If a company has elite leadership, strong strategic position, and a history of compounding value, friction and taxes can do more damage than patience.
This is especially relevant when:
Your cost basis is low
The company still has major optionality
The founder has repeatedly created value at a very high level
That logic was applied to both SpaceX and Anthropic. The argument is that these may be world-changing assets, and selling just because the valuation looks large can be a mistake if the business keeps outrunning expectations.
View two: scale out, never all out
The second approach is more trader-oriented and focuses on disciplined profit-taking.
The principle is straightforward: sell some into strength, never sell everything, and avoid letting a great gain turn into paralysis. This method accepts that calling the top is impossible, but still insists on harvesting value when markets become euphoric.
That philosophy was illustrated with a crypto example. After a sharp move higher in Ethereum, part of the position was sold, which funded a large personal purchase and a matching philanthropic commitment. The point was not lifestyle. The point was process. Realized gains can create optionality, reduce psychological pressure, and free capital for other uses.
In short:
Long-term investors focus on compounding and tax efficiency.
Tactical investors focus on rebalancing and asymmetry.
Both approaches work if executed consistently.
The real danger is not choosing one style or the other. The real danger is being undisciplined and switching frameworks in the middle of the cycle.
14.How to think about a possible SpaceX sale at these valuations
The direct question raised was whether it makes sense to sell SpaceX around a $1.25 trillion to $1.6 trillion valuation rather than waiting for an IPO near $1.7 trillion or $1.8 trillion and then facing a six-month lockup.
The cautious answer is that the valuation is already enormous relative to current revenue, and there may be easier doubles elsewhere. In that framing, taking some chips off the table is rational.
The more conviction-based answer is that Musk has repeatedly built businesses that looked expensive and then became much larger, and that selling too early has historically been a bigger error than holding quality too long.
Both positions are coherent. The deciding variable is investor identity.
If you are optimizing for:
Maximum participation in elite compounding, you hold.
Portfolio-level risk control and reallocation, you scale out.
There is no universal rule here. But there is a useful principle: pigs get fat, hogs get slaughtered. Extreme concentration in any asset can become a hidden risk, even when the company itself is excellent.
15.The deeper issue: society is not ready for the labor shift AI may create
The strongest long-term concern in the entire discussion was not valuation. It was social adaptation.
If AI productivity accelerates at anything close to the pace described, the challenge will not just be corporate implementation. It will be social restructuring.
That includes how we think about:
Employment
Retraining
Income security
Economic measurement
Political accountability
Markets may reward labor replacement quickly. Democracies often do not process labor displacement quickly. That gap can become the next major macro variable.
Investors need to understand both sides.
The market can be right about margins and still underestimate the political response to mass disruption.
16.Bottom line
The market is not ignoring layoffs, weaker confidence, or broader labor stress. It is interpreting them through a different lens.
Right now, the dominant view is:
AI is real
Productivity gains are coming faster than expected
Companies will need fewer workers to generate more output
Margins will rise
Equities, especially AI-linked assets, should be worth more
That is the bull case in its cleanest form.
The risk is that labor damage compounds faster than productivity benefits are socially absorbed. If that happens, confidence and politics can eventually hit growth hard enough to matter for markets.
For now, though, Wall Street is rewarding the efficiency story.
And that is why AI replacing workers is not being treated as a warning sign inside the market. It is being treated as a profit cycle.
Sources
[Anthony Scaramucci: AI Is REPLACING YOU and the MARKET LOVES IT
](https://www.youtube.com/watch?v=hsjEckj9kO8)
[New York Times: Companies and tariff refund reporting referenced in the discussion
IMPORTANT DISCLAIMER: This document is provided for informational and educational purposes only. It does not constitute investment, legal, tax, or other professional advice, and nothing herein should be construed as a recommendation, offer, or solicitation to buy or sell any security. Information is from sources believed reliable but not guaranteed; certain figures are estimates that may prove incorrect. Past performance is not indicative of future results, and all investments involve risk, including possible loss of principal. Conduct your own due diligence and consult a licensed professional before investing. Carlos Artiles accepts no liability for any loss arising from use of this material.
CARLOS ARTILES · Strategy. Growth. Life by Design.Informational use only — not investment advice

Comments (0)
No comments yet — be the first.