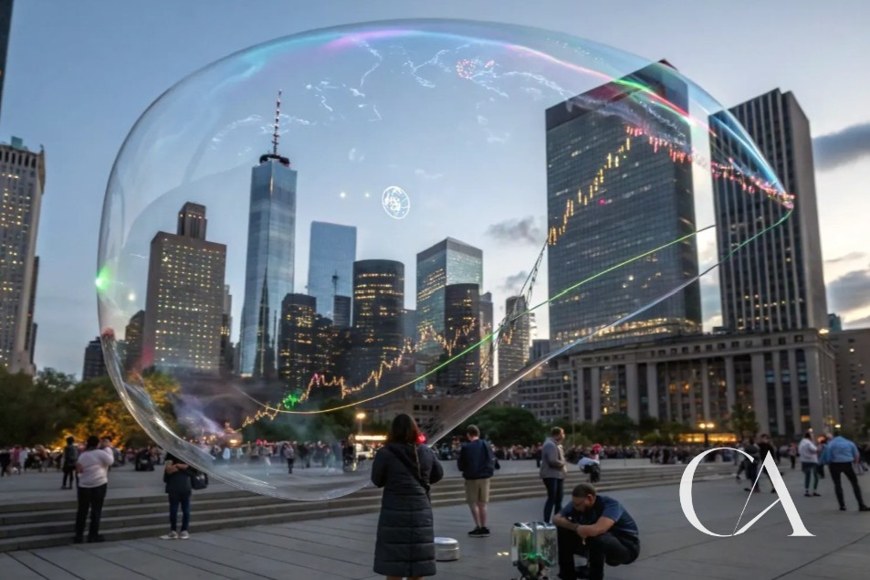
Why today's AI mania may be worse than it looks: circular financing, index mechanics and hidden leverage are inflating valuations and raising the risk of a sudden unwind.
Forty percent of every dollar you put into a vanilla S&P 500 index fund is concentrated in just ten names. Nvidia alone captures almost 8% of that dollar. Those ten companies: Nvidia, Microsoft, Apple, Alphabet, Amazon, Broadcom, Meta, Tesla, Berkshire Hathaway, and JP Morgan, are shaping not only equity returns but the broader narrative about the U.S. economy and AI.
1.What’s driving today’s AI mania
Markets have priced AI as if it will become the largest revenue engine in capitalism history. To justify current valuations, leading AI-related companies collectively need to generate roughly $2 trillion in annual revenue. For context, combining Apple, Amazon, Microsoft, Meta, Nvidia, and Google in 2024 did not reach that mark.
The market’s confidence is being backed by massive projected capital spending. Estimates put AI-related capital expenditures, building GPU farms, data centers, and AI infrastructure, near $330 billion in 2025. That spending fuels the narrative, which in turn justifies higher valuations, which in turn attract more capital. It is a self-reinforcing loop.
2.Circular financing: how the illusion of revenue is created
There is a financing mechanism at work that needs to be understood. Call it circular financing. It looks like this:
Large chipmakers and cloud providers invest in AI startups or make big contractual commitments.
Those AI startups commit to cloud contracts with major providers (Microsoft, Oracle, etc.).
Cloud providers respond by buying more GPUs and infrastructure from chipmakers.
The chipmakers appear to see increased demand and then invest more back into AI companies.
Money flows in a loop. It creates appearance of demand and growth even when much of that spending is funded by debt or off-balance-sheet structures like private credit, SPVs, joint ventures, and circular financing arrangements. That makes headline economic figures and index performance look healthier than underlying free cash flow would justify.
"Some level when something gets sufficiently huge whether or not they are on paper the federal government is kind of the insurer of last resort." — Sam Altman
When CEOs suggest strategic importance to the point of implying government backstops, they reveal how political economics and private capital interact. Strategic industries attract political support. That changes how risk is priced and how willing markets are to accept aggressive leverage and contingent arrangements.
3.Index mechanics amplify concentration
The S&P 500 is market-cap weighted. That means as the largest stocks appreciate, they take a larger share of passive funds that track the index. The more they grow, the more passive inflows they attract, which inflates their market caps, which attracts more inflows. Combine circular financing with passive allocation mechanics and you get a spiral of concentration.
Result: a handful of companies can dominate index returns and the perception of market health, even if underlying fundamentals are stretched.
4.Hidden leverage and the risk of "borrowing from the future"
Profitability and free cash flow are the only durable validators of valuation. When companies underwrite growth with rising debt and off-balance-sheet commitments instead of free cash flow, they are effectively borrowing from a future that must materialize for current valuations to hold. If that future revenue underdelivers, the unwind can be sudden and severe.
Indicators worth watching:
Private credit growth and SPV formation among large corporates and startups.
Large capex commitments financed via joint ventures instead of corporate cash flow.
Management rhetoric implying implicit government support for strategic tech.
5.Market veterans are signaling caution
Warren Buffett’s large cash position and the reported short positions placed by Michael Burry against names like Nvidia and Palantir are not trivial. When value investors and macro contrarians concurrently reduce exposure or place hedges, the market should take notice. They read fundamentals differently; one is selling discretionary exposure while the other is explicitly shorting high-conviction targets.
6.Is AI a bubble?
Define bubble: a rapid price increase disconnected from fundamentals. Under that definition, current AI-related pricing exhibits classic bubble characteristics — rapid appreciation, heavy narrative-driven flows, and financing structures that amplify appearance of growth.
But nuance matters. Large technological shifts create long-term winners while also producing speculative excess. The dot-com cycle is the template: the internet was transformative, yet valuations in the bubble period were detached and collapsed before fundamentals caught up. AI could follow the same pattern — structural transformation plus a speculative episode.
7.Bitcoin: a technical signal or a macro canary?
Bitcoin has diverged from tech equities recently, and that divergence is instructive. Two frameworks explain price action:
Technical analysis — Traders track indicators like the 50-week moving average. Falling below that trend line has historically signaled the end of bull cycles for Bitcoin and the start of extended bearish periods.
Macro liquidity dynamics — Bitcoin is often the first to react when liquidity is removed or when a liquidity transition occurs. Federal Reserve balance sheet reductions — quantitative tightening — remove systemic liquidity. An earlier-than-expected end to QT can be read psychologically as a sign of stress. That can push highly liquid, easily sold assets like Bitcoin down first.
Either framework can be correct simultaneously: technical selling begets macro scrutiny, and macro stress amplifies technical weak points.
8.What I am doing with capital, a practical plan
My approach is methodical and capital-preservative. That means:
Prioritize cash and liquidity: Increasing the cash position to buffer against volatility and to have dry powder for mispriced opportunities.
Maintain dividend reinvestment: Continue reinvesting reliable dividend income into quality positions to compound over long horizons.
Reduce leverage: No margin. No speculative, concentrated bets financed by debt.
Shift exposure selectively: Rotating a portion of real estate allocations into cash where timing and macro fragility justify it.
Avoid market timing: For long-time investors with 20 to 30 years of horizon, staying invested in diversified, high-quality assets tends to outperform attempts at short-term timing.
9.Actionable steps for investors
Follow these four steps to evaluate your exposure and reduce asymmetric risk.
Measure concentration: Calculate what percentage of your portfolio is in the top 10 market-cap names. If it exceeds your risk tolerance, rebalance.
Stress-test cash flow assumptions: For any equity that depends on future AI revenue, model a scenario where revenue growth decelerates by 30 to 50 percent. See whether current valuations still make sense.
Audit funding sources: Check whether a company’s capex and contract commitments are backed by free cash flow or by structured financing, SPVs, and private credit. Prefer firms funding growth through internal cash flow.
Maintain margin of safety: Use cash and high-quality bonds to preserve optionality. Avoid leveraged exposure to names reliant on circular financing.
Sources
Deutsche Bank analysis on AI spending and macro impact - search reports at https://www.db.com
Reporting on Sam Altman remarks - coverage available via major outlets such as Reuters and CNBC: https://www.reuters.com, https://www.cnbc.com
Michael Burry and 13F filings - filings accessible via the SEC EDGAR database: https://www.sec.gov/edgar
Federal Reserve balance sheet and QT explanations - Federal Reserve releases: https://www.federalreserve.gov
10.Bottom line
AI is real and has transformative potential. The current pricing, funding methods, and index mechanics, however, create a fragile system built on circular flows and hefty expectations. That combination concentrates risk across investors and the financial system. Take inventory of exposure, prioritize liquidity and free cash flow quality, and avoid borrowing to finance speculative bets.
Markets can remain irrational longer than anticipated. That makes discipline, conservatism, and a clear plan nonnegotiable.
IMPORTANT DISCLAIMER: This document is provided for informational and educational purposes only. It does not constitute investment, legal, tax, or other professional advice, and nothing herein should be construed as a recommendation, offer, or solicitation to buy or sell any security. Information is from sources believed reliable but not guaranteed; certain figures are estimates that may prove incorrect. Past performance is not indicative of future results, and all investments involve risk, including possible loss of principal. Conduct your own due diligence and consult a licensed professional before investing. Carlos Artiles accepts no liability for any loss arising from use of this material.
CARLOS ARTILES · Strategy. Growth. Life by Design.Informational use only — not investment advice

Comments (0)
No comments yet — be the first.