
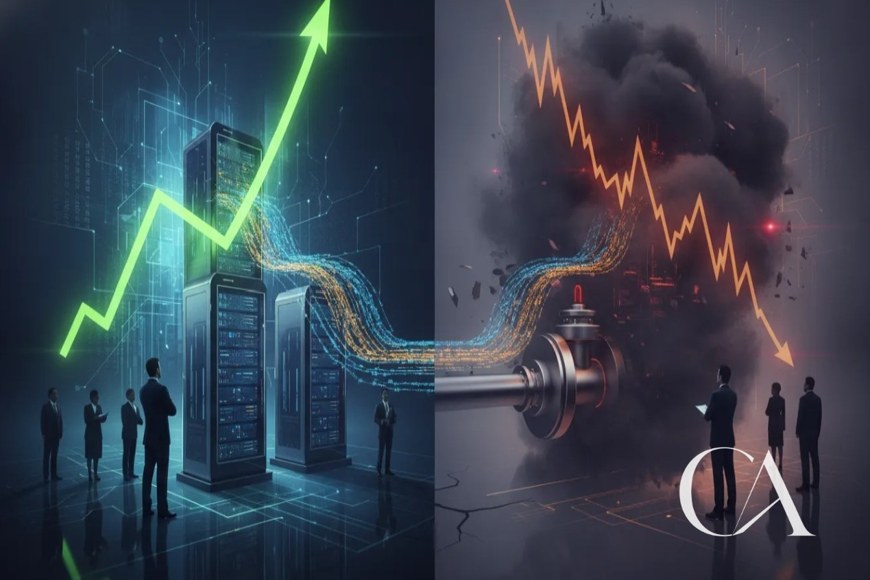
Equities are pricing relief while bonds are pricing policy risk. The old rules of capital scarcity are fading, but the risks did not disappear. They shifted.
This is not a normal market.
Stocks are pushing higher as if inflation risk has been neutralized. Bonds are signaling that policy risk is still very real. At the same time, companies are raising massive amounts of capital, AI infrastructure spending is breaking old valuation models, and a growing share of the market is being priced on expectations that may not survive contact with new supply, tighter policy, or slower profits.
Below is the framework that matters right now: why equities and bonds are sending opposite messages, how the new Fed is changing market behavior, why small caps are uniquely exposed, how AI is driving a historic capital cycle, why some software businesses are being repriced downward, and what all of this means for investors trying to allocate capital rationally.
- Equities rallied after a sharp drop in oil prices tied to easing geopolitical tension.
- The bond market is not buying the “all clear” narrative and is pricing meaningful odds of another rate hike.
- The Federal Reserve has moved away from predictable guidance and back toward strict data dependence.
- Small-cap companies are far more vulnerable than mega caps: much more of their debt is floating rate.
- Corporate finance has shifted from a buyback-driven era of scarcity to heavy issuance and debt funding.
- AI infrastructure is absorbing trillions in capex: chips, cloud, utilities, land, and power.
- Legacy software names are being repriced lower as AI threatens traditional interfaces and workflows.
- The labor market is being reshaped by AI-led efficiency, pressuring white-collar employment.
- Prediction markets are growing as investors seek a tradable way to price uncertainty itself.
The first split: stocks and bonds are telling different stories
The most important macro contradiction today is the gap between what the equity market is pricing and what the bond market is pricing.
Equities reacted positively to a major drop in oil prices after a U.S.-Iran peace framework helped reopen the Strait of Hormuz. Lower crude reduces shipping costs, eases manufacturing input pressure, and relieves consumers. In plain language, lower oil works like a short-term disinflation boost. That is the bullish equity case.
The bond market, however, is focused on something else: the Fed. Right now, bonds are signaling that policy could remain restrictive for longer than many stock investors want to believe.
“Stocks are cheering lower oil. Bonds are listening to the Fed.”
THE DIVERGENCE
Why the new Fed communication style changes everything
The change in leadership at the Federal Reserve is not cosmetic. It changes how risk gets priced across every major asset class. Under the prior framework, the Fed often telegraphed its likely moves well in advance, reducing uncertainty and letting participants position early. That is no longer the setup.
The current chair has emphasized pure data dependence: less forward signaling, more real-time policy reaction. For markets, that removes visibility. The practical consequences:
- Every inflation release matters more.
- Every labor print matters more.
- Every rate-sensitive trade carries more uncertainty.
- Bond yields can move faster because the market has less guidance to anchor expectations.
That uncertainty intensified when rate projections showed roughly half of Fed participants still expected rates could move higher by the end of 2026, a direct hit to the assumption that the rate cycle was a one-way path downward.
If bonds are right, small caps are the weak link
If rate risk rises again, small-cap companies are in a much weaker position than the largest S&P 500 names, and the reason is debt structure. A substantial share of Russell 2000 corporate debt is floating rate; the S&P 500 has much lower floating-rate exposure. Why that matters:
- Floating-rate debt resets upward when policy rates rise.
- Interest expense increases quickly.
- Profit margins get squeezed immediately.
- Smaller firms often lack the balance-sheet strength to absorb that pressure.
A mega cap with large cash reserves can withstand a rate shock far more easily than a small manufacturer, regional software business, or lower-margin industrial. If the bond market is correct and policy stays hawkish, small caps face the most direct earnings pressure.
The old market was built on buybacks. The new market is built on capital raising.
For roughly 15 years, one of the strongest structural supports for equities was corporate buybacks: companies reduced share count, shrinking supply and supporting prices. That era is fading. The market is shifting from stock scarcity to stock creation, issuing equity and taking on debt to fund AI infrastructure at enormous scale.
Demand for AI-linked financing has been exceptionally strong. Large bond deals tied to the buildout have met massive investor demand, which tells you two things at once: capital is abundant for the right narrative, and the market is willing to fund future AI growth aggressively even when near-term economics are uncertain.
The clearest example of phantom wealth: tiny float, huge valuation
The most extreme expression of this environment is using very limited tradable supply to create enormous paper valuations. If only a small percentage of shares are available, investors compete over a tiny float, pushing the quoted price sharply higher. The market then applies that elevated price to the full share count, including shares that are not freely trading.
When insider lockups expire and additional shares become tradable, supply increases. Historically, that often leads to material declines in newly public names, especially when the initial valuation was driven by limited float rather than broad price discovery. Investors buying at peak scarcity can end up providing exit liquidity for earlier holders.
There is a cultural layer too. U.S. capital markets are uniquely willing to fund high-risk, frontier-scale projects. That risk appetite enables breakthrough investment, but it also creates conditions where speculative pricing can detach from durable fundamentals for longer than most investors expect.
Where the money is actually going: the AI infrastructure supercycle
The new capital is not idle. It is moving directly into physical AI infrastructure, and the scale is enormous: by 2028, global AI data-center capex is projected to reach into the trillions. The market is funding a buildout that depends less on financial scarcity and more on real-world bottlenecks. Those bottlenecks are physical:
- Electric power and grid capacity.
- Land and cooling systems.
- Specialized construction labor.
- Advanced chips and memory.
This is why the winners in the current phase are often not the most obvious software brands. The market is rewarding the companies that supply the pipes, the compute, the memory, and the energy backbone: chip and memory makers, cloud infrastructure providers, utilities and grid-related companies, and cooling and energy-enablement businesses. The message is direct: if you are essential to building the infrastructure, you are in the money flow.
Why the Magnificent Seven can be flat while broader tech rises
At first glance it seems contradictory that equal-weight technology can outperform while the largest technology companies stall. It is not, once you separate spenders from beneficiaries. The mega-cap platforms are leading the AI race, but they are also paying for it, writing the checks for land, chips, power, data centers, and model development. That spending pressures near-term margins even if the long-term logic is intact.
Meanwhile, the broader tech ecosystem contains many of the companies receiving those expenditures directly. If capex is exploding, the firms supplying the ecosystem can outperform even while the largest sponsors of the buildout trade sideways. Mega caps fund the supercycle; infrastructure suppliers monetize its early phase; the market rewards whoever captures earnings first.
The SaaS repricing is real
On the other side of the trade, legacy software is under pressure. This is not just a rotation; it is a deeper valuation reset based on the belief that AI can remove the need for many traditional software interfaces. For years, SaaS created value by guiding users through structured workflows. Tax software is a clean example: the old model required a human to navigate forms, answer prompts, and complete a process step by step.
AI changes that. If a user can hand over raw documents and ask an advanced model to complete the task directly, the software layer in the middle becomes less valuable, and in some cases expendable. Investors are not waiting for full revenue damage to appear; they are discounting the risk now. A meaningful share of businesses already report measurable financial benefit from AI adoption, and early adopters are seeing earnings growth materially outpace non-adopters.
The global backdrop has changed: efficiency is out, resilience is in
This AI capex cycle is happening as the global economic model is rebuilt. The era of maximizing efficiency through deeply globalized supply chains is losing ground to a new priority: resilience. Governments and corporations are focused on making supply chains less fragile in a more divided geopolitical environment, which means more domestic production, more regional redundancy, and more strategic investment in critical industries such as semiconductors.
The result is higher capital intensity. Reindustrialization may support selected sectors, but it also raises costs relative to the old offshoring model. This is not simply an earnings story: it is a structural reallocation of capital across national priorities, industrial policy, and strategic production.
The labor market contradiction: higher profits, rising personal stress
One of the most important points in this cycle is that corporate strength and household strain can happen at the same time. Companies are using AI and prior over-hiring as justification for major layoffs, especially in white-collar roles. Less payroll plus more automation tends to support earnings. That is good for corporate profitability, but the same process can weaken household balance sheets:
- Job losses reduce income stability.
- Defaults on mortgages, auto loans, and credit cards can rise.
- Consumption pressure can emerge with a lag.
- Social and political friction increase as labor displacement becomes more visible.
This is the heart of the social-market disconnect. Wall Street can reward efficiency at the same moment Main Street absorbs the disruption. An economy can show expanding GDP and stronger aggregate profits while parts of the population experience severe financial pressure.
The market's logic is brutal but consistent
Markets do not allocate capital based on sympathy. They allocate it based on expected productivity, future cash flows, and relative return. Capital moves toward what the market believes will be most productive next. If that requires starving old business models and overfunding new ones, the market will do exactly that. This is why investors need a framework, not emotions. The current tape is dominated by three simultaneous forces: disinflationary relief from lower oil, persistent uncertainty from a less predictable Fed, and a massive AI-driven capex and valuation regime change.
Why prediction markets are growing so fast
As uncertainty rises, investors look for new tools to price it, which helps explain the rapid expansion of prediction markets. These platforms turn political events, macro outcomes, and policy decisions into tradable probabilities. The deeper point: the more investors try to convert uncertainty into a price, the more they reveal what markets are fundamentally built on, which is risk. Risk is not a flaw in the system. It is the engine of the system.
What this means for investors right now
The right approach is not panic. It is selectivity. Focus on the actual fault lines:
| Rates sensitivity | Small caps and floating-rate borrowers remain more exposed than mega caps. |
| AI capex beneficiaries | Hardware, memory, cloud infrastructure, utilities, and energy-linked enablers remain central to the buildout. |
| Software vulnerability | Businesses dependent on old interfaces or rigid workflow models face real repricing risk. |
| Valuation quality | Be careful with companies whose market caps are driven by restricted float and scarcity optics rather than genuine supply-demand balance. |
| Labor & credit stress | Rising corporate efficiency does not eliminate consumer-side fragility. |
The key mistake now is to treat this market like a standard late-cycle rally. It is not. This is a regime transition in capital allocation, policy signaling, industrial investment, and labor economics.
Bottom line
The market is being pulled in opposite directions. Stocks are celebrating lower oil and the growth potential of AI. Bonds are warning that the Fed remains a serious source of risk. Corporations are raising huge sums and deploying them into infrastructure that could define the next decade, yet that same spending wave is creating valuation distortions, crushing parts of software, and accelerating labor disruption.
The winners will likely be the businesses controlling physical bottlenecks, scarce infrastructure, and real productivity gains. The losers will be firms dependent on old interfaces, weak balance sheets, or valuations that only work under perfect conditions.
SOURCES
Federal Reserve Board. Monetary policy communications and rate projections, federalreserve.gov/monetarypolicy.htm
U.S. Energy Information Administration. Oil market data, eia.gov
U.S. Securities and Exchange Commission. IPO and disclosure framework, sec.gov
PIMCO. Insights and macro commentary, pimco.com
CHIPS Program Office. U.S. semiconductor industrial policy, nist.gov/chips

Comments (0)
No comments yet — be the first.